Home / Section 179
Commercial Roofs and Section 179, in Plain Terms
Roofs on non-residential buildings have been treated differently since the 2017 rules changed, and roof work is one of the categories that comes up most often in that conversation. We are roofers, not accountants. Confirm all of this with your own tax advisor before you rely on it.
- Free, photo-documented roof assessment
- Restore and replace numbers, every time
- Warranties honored the full term, up to 20 years
Certified To Install
You have probably
been here before.
The leak keeps coming back.
It gets patched, it holds through one dry spell, and it is back the next time the wind drives rain the wrong way.
We find where the water actually gets in before anyone quotes you a system.
The replacement quote made you wince.
A full tear-off was quoted on a roof that may not need one, and nobody showed you the condition of the deck.
We say so when a roof does not need replacing, even though replacing it pays us more.
You were talked over, not talked to.
Mil thickness, ponding ratios, a system name you were told to trust. You are responsible for the building and cannot check a word of it.
Nothing happens on your roof without you knowing first. That is the rule here, not a slogan.
That is the one that costs the most and it is the reason this company exists. The contractor who came in sixty thousand dollars cheaper than us on a roof nearby is no longer trading. We are the ones installing the replacement.
Ask us who services your roof in year three. It is the only question on this page we can answer with a name.
Because Nobody Else Raises It Before the Decision
The roofing conversation and the tax conversation almost never happen in the same room. The result is that owners compare two quotes on price, sign, and only afterwards find out the two options would have been treated very differently.
This page exists to get the question asked early. Not to answer it.
What Your Accountant Actually Reads
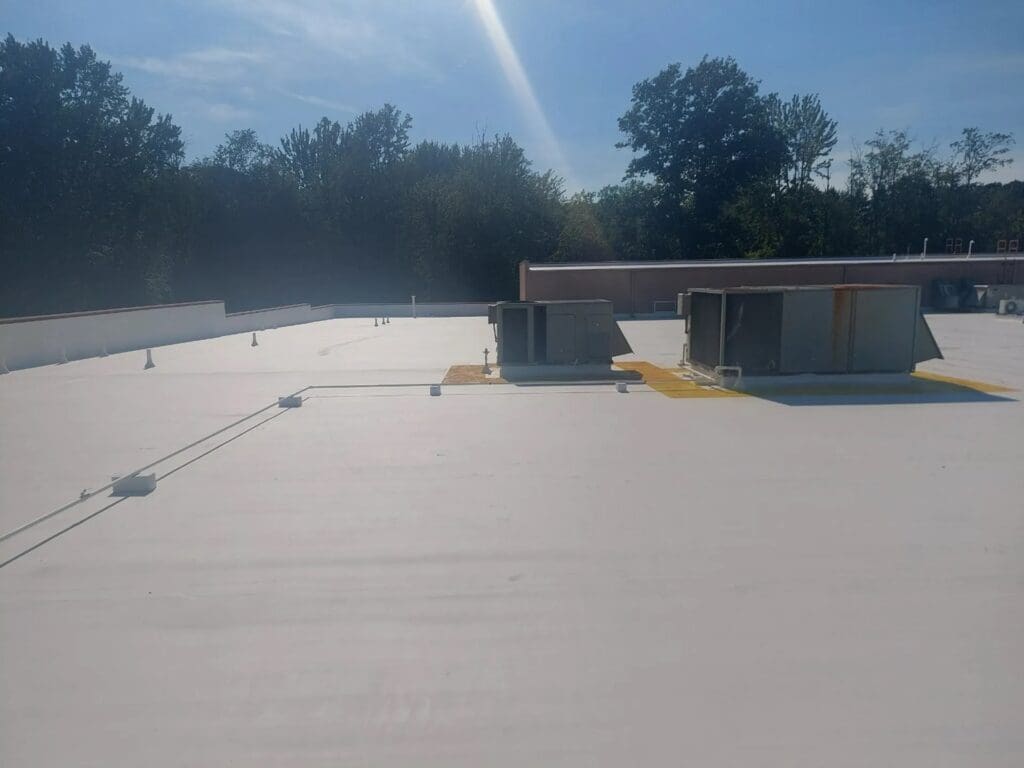
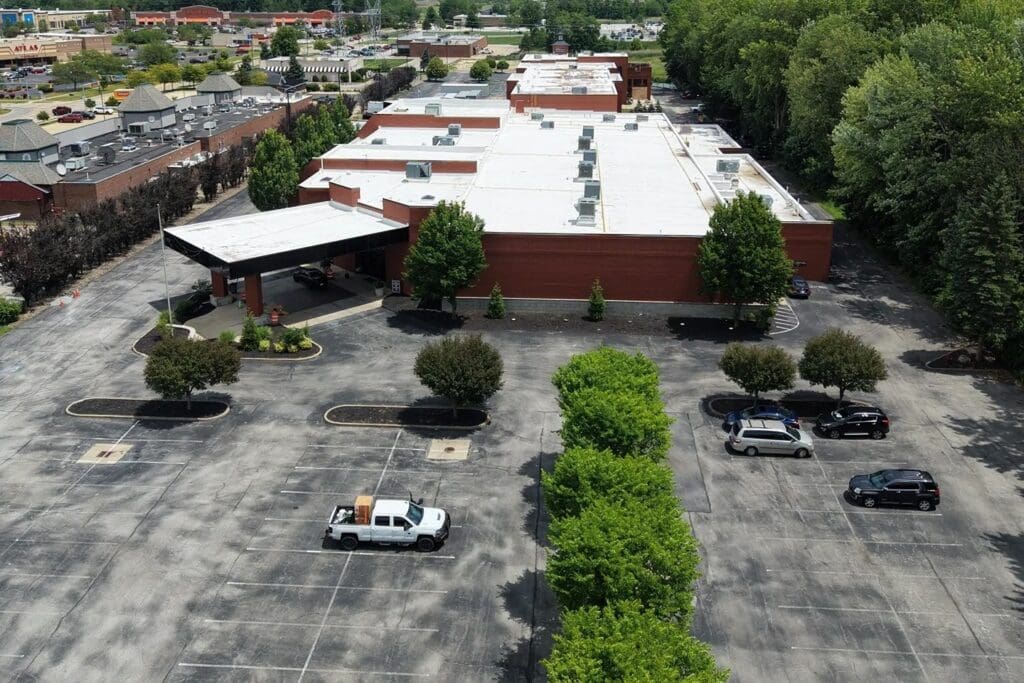
Treatment follows the work, not the label on the invoice. Cleaning, resetting fasteners, cutting out wet insulation, reinforcing seams and coating a roof that stays in place is a different thing from removing a roof and building a new one.
So the scope has to be specific and honest. Ours is, because it has to survive both your accountant and the manufacturer’s warranty registration.
Three Things Worth Knowing Before You Call Your CPA
Roofs on non-residential buildings became eligible property.
The 2017 changes brought certain improvements to non-residential real property, roofs among them, into the category that can be considered for immediate expensing rather than long depreciation. Whether it applies to you depends on facts we do not have.
Eligibility is not the same as benefit.
There are limits, thresholds and income tests, and a deduction is only worth something against income to deduct it from. This is precisely the part your accountant is for, and it is why no roofer should be telling you the answer.
Restoration may not need this conversation at all.
If the work is treated as a maintenance expense in the year performed, the question of capitalizing it and then accelerating the depreciation does not arise in the same way. That is the other route and it is often the simpler one.
Four Steps, and We Are Not Step One
Ask your tax advisor the direct question
Whether this roof work on this building, treated this way, is eligible, and whether it is beneficial given your position this year. Both halves matter.
Give them the written scope
Not a summary. The treatment follows what is actually being done to the roof, so they need it described properly. We will put it in writing for exactly this purpose.
Ask about timing
These questions are frequently about which tax year the work lands in. That is worth knowing before scheduling, not after.
Keep the documentation
Scope, photographs, invoice and warranty registration, filed together. The same records that support the tax position also keep the warranty enforceable.
Section 179 Questions
Straight answers on cost, timeline, and what a restoration actually involves. No jargon, no sales pressure.
A free, photo-documented assessment and honest numbers on restore versus replace.
Is this tax advice?
No. We are a roofing company and this page exists so you know to raise the question, not so you can rely on it. Confirm everything here with your own tax advisor, who can apply the actual rules to your actual return.
Does a roof qualify?
Roofs on non-residential buildings are among the improvement categories that became eligible under the 2017 changes. Whether yours qualifies, and whether the deduction is useful to you, depends on limits and on your own tax position. Your CPA answers both.
Is it better than treating the work as maintenance?
Genuinely depends, and it is worth asking about both routes rather than assuming. A restoration expensed as maintenance and a capitalized improvement with accelerated deduction are different mechanisms with different outcomes. Ask which applies to the work you are actually buying.
Does this change what roof you should buy?
It should not. Get the roof decision right on the roof’s merits, then optimize the treatment. We recommend restoration when the roof will carry it and replacement when it will not, and the tax position is not a reason to coat something that needs replacing.
What do you need to provide?
A written scope describing the work as it will be performed, the system and thickness specified, the invoice, and the warranty registration afterwards. Ask and it comes in that form.
Start With the Truth About Your Roof
Request your free, photo-documented roof assessment. Honest options, firm numbers, and a roofer who will still be here next year.
Free assessment · Photo-documented · No obligation, no pressure